
Chicago O'hare
IHG Crowne Plaza Hotel
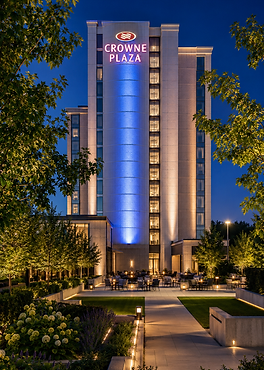
Treme-Parker is seeking a $47,191,607 senior secured first-lien leasehold facility, to fund the acquisition and historic redevelopment of a 503-key full-service hotel at the doorstep of O'Hare International Airport into the only dual-brand Crowne Plaza and Hotel Indigo in the Chicago market.
The Location Is the Asset
Five hundred and three keys on a full block in Rosemont, Illinois, four hundred yards from the eight-hundred-and-forty-thousand-square-foot Donald E. Stephens Convention Center and one transit stop from O'Hare International Airport. This is a village of four thousand two hundred residents that welcomes between seventy-five thousand and one hundred thousand visitors every day and to which more than sixty thousand people commute to work. It has organized its land use, its tax base and its governance around a single purpose: importing demand.
The demand arrived and kept arriving. O'Hare moved 84.85 million passengers in 2025, exceeding its 2019 peak, after posting the largest passenger gain in the Americas the year before. Chicago welcomed 55.3 million visitors in 2024 generating $20.6 billion of economic impact, booked 1,891 conventions and contracted 2.65 million future convention room nights. The convention center four hundred yards away hosts approximately one hundred exhibitions a year across 840,000 square feet, roughly two compression events every week of the calendar. Add the Allstate Arena, the Rosemont Theatre, the Fashion Outlets of Chicago and the Parkway Bank Park entertainment district, all within walking distance, and the submarket generates weekend leisure compression layered on top of midweek corporate and convention demand.
This is one of the deepest and most durable lodging demand bases in the American Midwest, and the subject sits at the center of it with a full conference center, a Restaurant Space, a Starbucks license and a liquor license already in place.

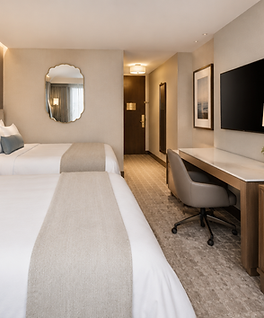
Hospitality Summary
-
503 Keys
-
14 Stories
-
3 Food & Bev Spaces
-
Chef Driven Restaurant
-
Starbucks
-
Visibility Bar
-
Bill Murray's Caddy Shack
-
23k sf Main Ballroom
-
5 Meeting Spaces
-
Fitness Center
-
Business Center
-
Conference Rooms
-
Outdoor Green Space
-
Indoor Pool


The Opportunity Is Precise and Measurable
The property today carries a rate index of 83 to its competitive set while simultaneously out-rating the broader O'Hare upscale industry by better than ten percent. It beats the neighborhood and trails its own block, and the gap is entirely a function of product vintage rather than position.
Two components account for nearly all of it, and both are specific. The property sells group business at $144.83 into a competitive set clearing $184.56 while holding conference facilities a four-minute walk from the second-largest exhibition center in Illinois. And it prices midweek at a 4.9 percent premium to weekend against a set that prices midweek at 9.7 percent, on nights when the set runs seventy-four percent occupancy. The first requires new product. The second requires only a rate calendar. Neither requires a market forecast, a demand study, or a single new visitor to Chicago.
The absorption requirement quantifies how modest the lift is. Reaching stabilized occupancy requires capturing 0.95 percent of corridor room nights the property does not win today, from a competitive set already operating at 68.8 percent occupancy while the subject operates at 55.0 percent.
IHG Has Already Underwritten This With Its Own Balance Sheet
IHG is contributing $10,750,000 of key money, or $21,372 per key, against a customary conversion band of $2,000 to $10,000 per key. It has reduced application fees by eighty-four percent and granted thirty-year license terms on both flags. This is roughly double the top of the market from an investment-grade brand owner, committed before a dollar of third-party debt.
The structure explains the conviction. Hotel Indigo is IHG's boutique conversion brand, and 197 keys of it will enter a corridor of approximately twelve thousand rooms that today offers no boutique, no lifestyle and no design-led alternative of any kind. The upper-upscale Indigo pulls the rate of the 306-key Crowne Plaza alongside it, while the Crowne Plaza retains the conference center and the group apparatus. Two flags, one loyalty account, one management company, and an empty category to enter rather than a crowded one.


The Credit Is Materially Over-Collateralized
Stabilized net operating income of $15,007,211 covers annual debt service of $3,972,457 by 3.78 times. The debt yield is 31.80 percent against a ten percent covenant. Loan-to-value is 26.73 percent against a sixty-five percent covenant. Every covenant clears in every year of a ten-year projection, with the minimum coverage of 2.33 times and the minimum debt yield of 17.32 percent both occurring in the first operating year while the property is still ramping.
The facility is sized at fifty percent loan-to-cost against a maximum supportable loan of $61,349,089. Loan-to-cost is the binding constraint; every cash-flow-based sizing test permits more than twice the requested amount, leaving $14,157,482 of unused capacity as pure protection.
Fifty percent of the capitalization sits junior to this facility, and $23,083,262 of it is non-dilutive subsidy rather than equity that can walk: $10,750,000 of IHG key money, $12,383,262 of federal and state historic tax credit equity, and $3,875,936 of deferred fees. Behind that stands $20,182,409 of first-loss cash at 21.38 percent of cost.
The stress work is uneventful, which is the point. Across a full matrix running to four hundred basis points of rate shock and a forty percent income haircut, there is no cell that breaches covenant; the most punitive combination available holds coverage at 1.60 times. A severely adverse scenario combining three hundred basis points of rate shock, a thirty percent income reduction and a thirteen percent exit capitalization rate leaves coverage at 2.02 times.
Exposure is $93,821 per key. Every Chicago full-service hotel that traded in 2026 cleared between $121,690 and $128,000 per key, and those were unrenovated assets carrying undisclosed improvement liability. This facility lends beneath the market's current floor for materially inferior product, into an asset that will deliver new.



Two Independent Exits, Each Sufficient Alone
A stabilized refinance sizes to $105,933,257 bound by loan-to-value, covering the facility balance 2.15 times and returning 280.9 percent of common equity while still carrying 1.68 times coverage at the permanent level. An institutional sale at the underwritten twelve percent exit capitalization rate, three hundred and fifty basis points above the current full-service market, produces $137,525,767 of gross proceeds and covers the facility 2.93 times. Across a four-and-a-half point range of exit capitalization rates the facility is repaid in full at every point.
Supply Cannot Respond
Chicago metropolitan supply grew approximately 0.7 percent over the trailing year against a construction pipeline of about 1.5 percent of inventory. Lodging Econometrics records no new-build full-service hotel under construction anywhere in the O'Hare corridor. Not one hotel in the six-property competitive set has opened since 2008. This asset will hold the newest full-service product in the market on delivery, and any competitive new-build requires three to four years from site control to opening, placing it beyond both stabilization and exit.
The Argument
A fifty percent loan-to-cost facility at a 15.90 percent yield on cost, lent beneath the market's clearing price per key, behind $47.2 million of junior capital of which half is subsidy from an investment-grade brand owner and two levels of government, secured by the only dual-brand hotel in a corridor moving eighty-five million passengers a year with nothing new under construction and nothing new since 2008. The transaction does not ask a lender to believe the property will become exceptional. It asks only that a fifty-million-dollar renovation and two new IHG flags will lift a well-located, well-scaled, conference-anchored hotel to the level of the six competitors it already sits beside. IHG has staked $10.75 million on that proposition. The coverage says a lender is protected many times over whether or not it proves conservative.
Credit Summary
-
Total Project Cost: $94.4M
-
GP Equity: $20.2M
-
Key Equity: $10.75M
-
HTC Equity: $12.4M
-
LTC: 50%
-
Bridge Debt: $47.2M
-
Rehab Period: 12 mos
-
Year 1 NOI: $8.2mm
-
Year 1 ADR: $155
-
Year 1 Debt Yield: 17.3%
-
Year 1 Yield on Cost: 8.6%
-
Year 1 DSCR: 2.33x
-
Stabilization 48 mos
-
Stabilized NOI: $15M
-
Stabilized ADR: $251
-
Stabilized Debt Yield: 31%
-
Stabilized Yield on Cost: 15.8%
-
Stabilized DSCR: 3.78x
-
Stabilized Value: $125M
-
Year 6 NOI: $15.9M
-
Year 6 ADR: $266
-
Year 6 Debt Yield: 33%
-
Year 6 Yield on Cost: 16.8%
-
Year 6 DSCR: 4.02x
-
Levered IRR: 54%
-
Avg Cash on Cash: 55%
50%
Loan to Cost
17.3%
Minimum Debt Yield
$3.9M
Break Even NOI (DSCR=1x)
2.53x
DSCR Cushion+1.25x