
Hotel Avec Traverse City
Hilton Tapestry Collection
Treme-Parker is pleased to present a compelling $17.2 million limited partner equity opportunity in Hotel Avec, a 114-key upscale boutique hotel operating under the Hilton Tapestry Collection, rising on the last downtown Traverse City parcel that carries both Boardman River frontage and Grand Traverse Bay views. Total development cost is $72,280,535, or $634,039 per key. The sponsorship is offering up to $14.3M of limited partner equity alongside its own $4.3M co-investment, against $46,982,348 of third-party construction debt and $3,693,803 of grants, brand key money, and subordinate state support. The investment thesis does not rest on a demand story that must first be proven. Traverse City draws 7.3 million visitors a year against a resident population of roughly 15,000, and there is no comparable upper-upscale hotel within a seventy-five-minute radius. The demand arrived a decade ago; the product to capture it at rate has not. This offering finances the berth, not the harbor.
The Market
Traverse City has become the Midwest's premier four-season destination, and the underlying metrics carry the argument without embellishment. Visitation reached 7.3 million in 2022, up five percent year over year and eleven percent above pre-pandemic levels. The city's population swings roughly fifty percent between February and July. Cherry Capital Airport moved more than 700,000 passengers in 2023 and posted a record year in 2024. The demand base is unusually diversified for a resort market: more than fifty wineries and twenty breweries, Sleeping Bear Dunes National Lakeshore drawing 1.5 million annual visitors, and the National Cherry Festival concentrating over 500,000 visitors across eight days. Summer beaches, autumn foliage, winter skiing, and a year-round culinary economy give the market four distinct seasons of demand rather than one. Traverse City was named a must-see world destination in 2025 alongside Maui, Morocco, and Malta, and ranks among Bon Appétit's top five foodie towns in America. Against all of that, the entire upper-upscale segment sits empty.
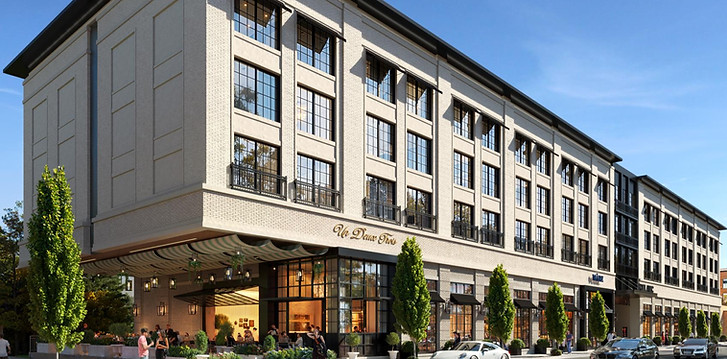
Hospitality Summary
-
114 Keys
-
4 Stories
-
10k sf of Food & Bev
-
Chef Driven Restaurant
-
Rooftop Bar w/ River & Harbor Views
-
Speakeasy Lounge
-
Designer Ballroom
-
Fitness Center
-
Business Center
-
Conference Rooms
-
Outdoor Green Space
-
Cafe w/ Outdoor Street Terrace


The Site and the Asset
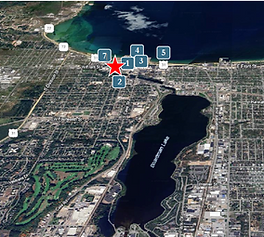
The asset occupies a brownfield redevelopment site in the Front Street District, waterfront-adjacent, steps from Clinch Park Beach, and walkable to the whole of downtown. Every guestroom carries river views, bay views, or both. The food and beverage program runs 10,000 square feet across four distinct concepts: a chef-driven signature restaurant with prime street-level Front Street exposure, a French café concept already proven in the sponsorship's portfolio and imported here, a rooftop bar overlooking both the river and the bay, and an intimate lower-level speakeasy lounge. Meeting and ballroom space, outdoor fire features, and a curated lobby complete the program. The site itself is the durable competitive advantage. No remaining downtown parcels offer dual water exposure, and the remediation cost and entitlement burden that the sponsorship has already cleared stands as a permanent toll on any future entrant. Scarcity of this kind does not depreciate; it compounds.
Competitive Position
Trended to a common September 2023 reporting period, the subject underwrites to the highest average daily rate and RevPAR in its competitive set, at $260 to $265 and $190 to $195 respectively, on seventy-five percent occupancy. The nearest lifestyle competitor, a 107-key branded hotel three-tenths of a mile away, achieves $240 to $245 in rate and $180 to $185 in RevPAR. A 281-key independent resort lodge nearly three miles southwest reaches $245 to $250 and $185 to $190. The balance of the set, comprising select-service and midscale product between 2.6 and 4.0 miles from the site, runs $175 to $190 in rate and $105 to $140 in RevPAR at occupancies as low as fifty-five percent. The subject's projected premium of roughly eight percent over the closest competitor is not aspirational positioning. It is the arithmetic consequence of a superior location, a materially higher finish level, and a food and beverage program with no analogue in the market.


Capitalization and Non-Dilutive Capital
Total sources of $72,280,535 comprise the $46,982,348 construction loan at 65.0 percent of cost, $17,283,506 of limited partner equity, $4,320,877 of sponsor equity, $950,000 of Hilton Tapestry brand key money, an $837,811 Clean Michigan Initiative brownfield loan, and $805,189 in Renew Michigan and Refined Petroleum Fund grants. Equity and non-dilutive capital together total $26,502,831, or 33.9 percent of cost. The $2,593,000 of grants, key money, and subordinate support represents better than ten percent of the hard equity in the deal, capital that reduces basis without diluting a single limited partner. Layered above it is a five-year municipal tax increment financing reimbursement under Downtown Traverse City's Moving Downtown Forward TIF Plan, delivering approximately $500,000 per year, or roughly $2,500,000 cumulatively, arriving precisely across the ramp years when a new hotel most needs it. On the uses side, $46,982,348 funds the general contract, $9,944,754 the furniture, fixtures, and operating supplies, $3,441,930 developer overhead, $3,450,000 land, $2,059,000 architecture, engineering and interior design, $2,562,017 preopening expense, $2,562,017 interest carry, $2,105,258 contingency, and $1,581,377 permits, legal, franchise, and closing costs. Preopening and carry are funded inside the budget rather than deferred to operations, which is the difference between a ramp that is financed and a ramp that is endured.
Operating Underwriting
The pro forma opens in 2028 at 59.9 percent occupancy and a $277 average daily rate, producing $15.1 million of revenue and $4.85 million of net operating income, or $5.33 million inclusive of TIF reimbursement. Occupancy reaches 74.0 percent in 2029 and stabilizes at 78.0 percent from 2030 forward, a level the two closest competitors already achieve today without the subject's product advantage or Hilton's global reservation and loyalty distribution. Stabilized net operating income is $6.52 million in Year 3, or $7 million with TIF, on $18.79 million of revenue. By Year 10 revenue reaches $23.15 million and net operating income $7.68 million, with underwritten asset value rising from $60.58 million at in-service to $93.12 million. Levered cash-on-cash runs 7.78 percent in the first partial year and climbs to 13 percent the year after, averaging 14.34 percent across Years 1 through 10. The cumulative equity multiple crosses 2x in 2031 and reaches 3.18x by 2035.


Sponsor
Hospitality
Track Record
Structure, Waterfall, and Alignment
Limited partners receive an eight percent per annum preferred return, cumulative and non-compounding, paid pari passu between the sponsor and the limited partnership. Preferred return is followed by full return of invested capital, after which residual proceeds split eighty percent to equity investors and twenty percent to the sponsor as promote. Modeled to a Year 12 exit at a 7.75 percent capitalization rate, limited partners receive $14,779346 of preferred return, $17,283,508 of returned capital, and $28,049,773 of residual proceeds, for total distributions of $60,112,626 against $17,283,508 invested, a 3.48x gross multiple. Annual distributions commence as cash flow permits following stabilization. The alignment is structural rather than rhetorical: the sponsor invests twenty percent or more of required equity in every project it undertakes and has done so here at $4,320,877, subordinating its promote entirely to the delivery of investor preferred return and capital.
Sponsorship and Operations
Sponsorship carries $1.2 billion in assets under management, $1.58 billion under active development, 53 assets across more than twelve states, and a 1,072-key hospitality pipeline. Its hotel leadership team has collectively developed more than $6 billion of hotels and over 10,000 guestrooms across more than eight states, with over one hundred combined years of hospitality experience drawn from Marriott, Westin, Sheraton, Kimpton, InterContinental, and a national hotel development platform. Day-to-day operations will be handled by a third-party hospitality manager operating 8 hotels and 16 restaurants across 7 states, with a demonstrated command of the food and beverage side that this asset's four-concept program demands. Sponsor identity, full track record, and operator credentials are disclosed under executed confidentiality agreement.
Timeline
As underwritten, equity and construction loan closing occurs in the third quarter of 2026, construction commences in the fourth quarter of 2026, and the hotel opens in the third quarter of 2028, with stabilization achieved by 2030 and a targeted exit in Year 12. Investors should note that the sequencing is deliberately built to deliver into a peak Traverse City season from opening day.
The Argument
Most hospitality development asks an investor to fund a market position that must first be won. This one asks an investor to fund the only product capable of serving a market that has already proven itself, on the only site in that market where such product can still be built. The capital stack carries 65 percent leverage against a basis reduced by $2.59 million of non-dilutive support, with a further $1.1 million of municipal reimbursement layered across the ramp. The sponsor stands beside the offering with twenty percent of the equity and behind it with a fully subordinated promote. Underwriting stabilizes at an occupancy the competition already achieves, at a rate premium the asset plainly earns. Scarcity is the rarest input in real estate; here it is the foundation rather than the aspiration.
Investment Summary
-
Total Project Cost: $72.3M
-
GP Equity: $4.3M
-
Key Equity: $950K
-
LP Equity: $17.2M
-
LTC: 65%
-
Construction Debt: $47M
-
Construction Period: 18 mos
-
Stabilization: 36 mos
-
Year 1 NOI: $5.3mm
-
Year 1 ADR: $277
-
Year 1 Debt Yield: 9.36%
-
Year 1 Yield on Cost: 7.69%
-
Year 1 Cash on Cash: 7.78%
-
Stabilized Value: $80M
-
Stabilized Equity Multiple: 1.83x
-
Year 5 NOI: $7.34M
-
Year 5 ADR: $312
-
Year 5 Yield on Cost: 10.58%
-
Year 5 Cash on Cash: 15.97%
-
Year 5 Equity Multiple: 2.36x
-
Year 10 NOI: $7.68M
-
Year 10 ADR: $362
-
Year 10 Yield on Cost: 11%
-
Year 10 Cash on Cash: 17.8%
-
Year 10 Equity Multiple: 3.87x
-
Year 10 Value: $93.1M (7.75% CAP)
-
LP IRR: ~13.64%
*Project Returns
$14.8M
Preferred Return (8%)
$17.3M
Return on Equity
$28M
LP Proceeds
$60M
Total LP Distributions